Banking and lending software built for review and audit
Loan origination, digital onboarding, KYC refresh, fraud dashboards, open banking, treasury, collections and back-office consoles over the core. Every build listed here is a real product we designed and built.
What banking and lending software has to get right
Banking software is judged on two things at once: how fast a customer gets an answer, and whether every decision can be explained to an auditor later. Most of the problems we see come from work that moved to email and spreadsheets because the core system could not change fast enough.
The systems below take that work back into software: one record per application or case, rules that are versioned, maker-checker on anything that moves money or changes a customer, and a log of who decided what.
Problems we are asked to fix
The problems teams bring to us, the system that fixes each one and the builds that did it.
Loan origination system
Loan applications take days because underwriting, document checks and approvals run by email and spreadsheets.
One application record from intake to funding, with document checks, a credit decision that shows its reasons, and approvals with a clear owner.
KYC refresh platform
Periodic KYC reviews pile up and customers get blocked because refresh is manual.
Reviews scheduled by customer risk, triggered by events, and asking customers only for what changed.
Digital onboarding
Customers abandon account opening midway through ID checks and forms.
ID and liveness checks inside the flow, save and resume, and manual review only when the risk calls for it.
Fraud case dashboard
Fraud teams drown in false-positive alerts and miss real fraud.
Alerts grouped into cases and sorted by risk, with the customer's history and the reimbursement decision in one place.
Open banking aggregator
Connecting to many banks' open banking APIs with different formats and consent rules.
One connector layer that normalises bank APIs and consent renewals, with an operations console for failing connections.
Treasury and cash management
Finance teams cannot see cash across banks because statements arrive in MT940 and camt files.
Statements from every bank parsed into one cash position, with dual authorisation on outgoing payments.
Collections platform
Collections teams chase late payers with manual call lists.
Work queues by stage and risk, with contact rules such as time windows and frequency limits enforced by the system.
Back-office console over the core
Back-office staff work around an old core banking system that is hard to change.
A modern console that reads and writes to the core through APIs, with maker-checker on every change.
15 kinds of banking and lending system we have built
Each one links the product build behind it, counted from our case studies.
- Falaj - Treasury & cash management
- Keelstone - Core banking back office
- Keystep - Digital bank onboarding
- Lastro - Credit scoring engine
- Lendwell - SME loan origination
- Lintel - Mortgage portal
- Lotse - Open banking aggregator
- Mooring - Collections & recovery
- Njia - Branch & ATM analytics
- Pasje - Card issuing & controls
- Quartet - BNPL checkout
- Sampan - KYC refresh automation
- Tarang - Consumer lending app
- Tidemark - Fraud detection dashboard
- Weaver - Relationship manager 360
Banking and lending products we built
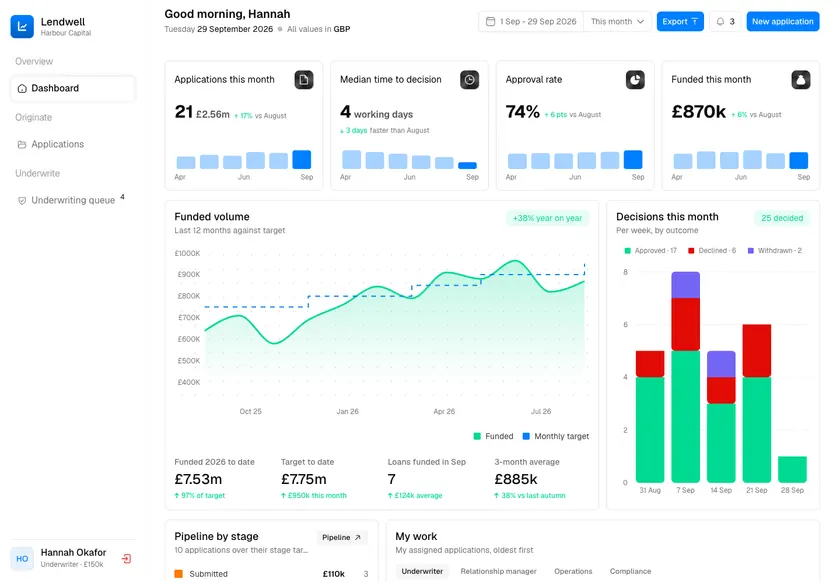
Lendwell - SME Loan Origination from Application to Funded
A loan origination platform for Harbour Capital, a UK digital lender offering £25,000 to £500,000 term loans to small businesses - one workspace for applications, KYB and KYC, open banking and bureau data, underwriting, credit committee, offers and funding.
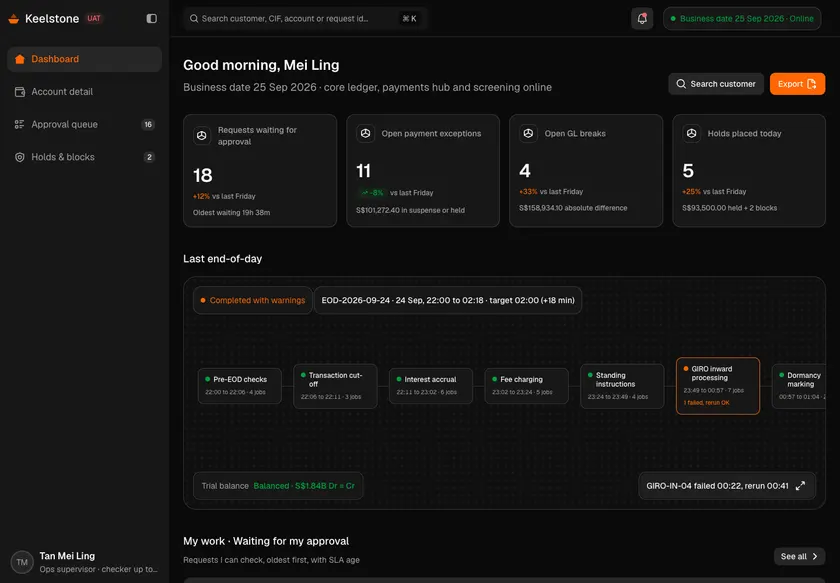
Keelstone - Core Banking Back-Office Console with Maker-Checker
Designed and built a clickable back-office console for a Singapore bank's deposit operations: holds and blocks, limit changes, fee waivers, payment repairs and end-of-day, with every money-moving change going through maker-checker approval.
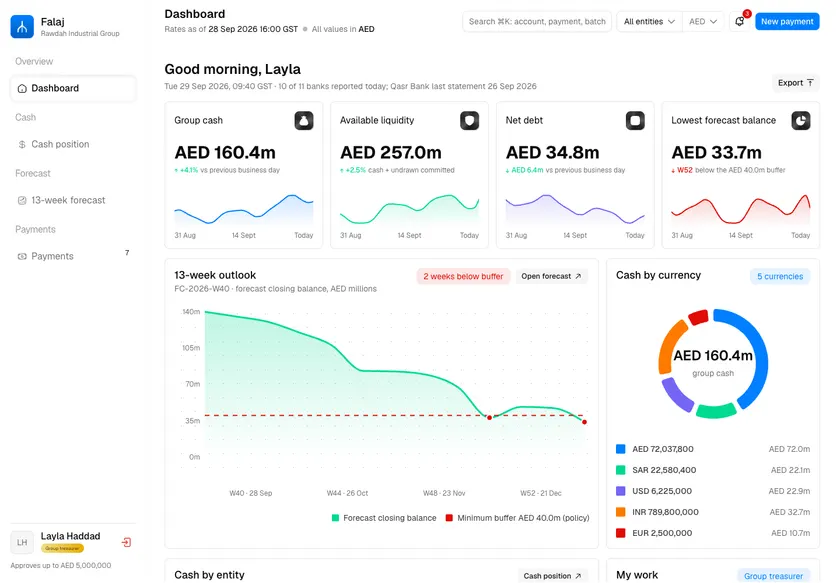
Falaj - Multi-Bank Treasury and Cash Management Platform with Dual Authorisation
Designed and built a clickable treasury platform for a Dubai-headquartered group with companies in the UAE, Saudi Arabia and India: one daily cash position across 11 banks in AED, a rolling 13-week forecast, and outgoing payments that go through dual authorisation before they are released to the bank.
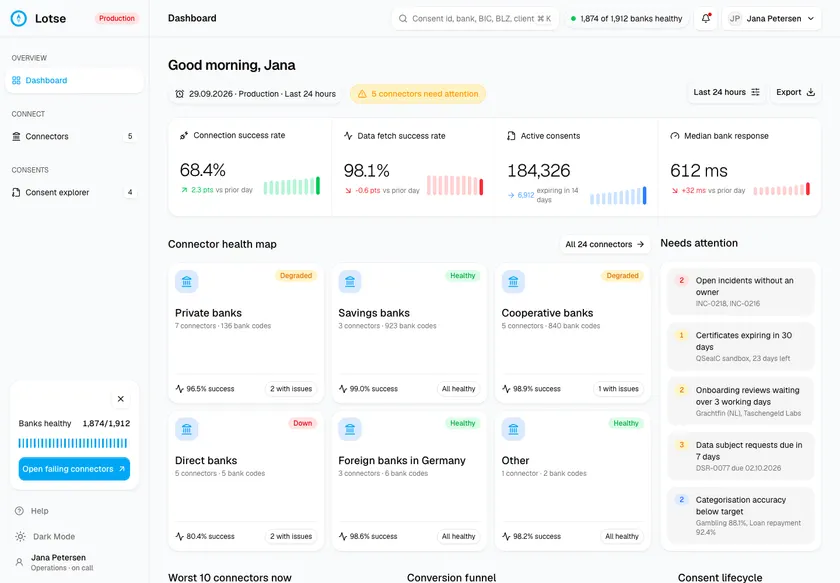
Lotse - Open Banking Aggregator Operations Console
Designed and built a clickable operations console for a Hamburg account information service provider that connects fintechs to German bank accounts under PSD2: bank connector health, incidents, and every consent from grant to the 180-day re-authentication.
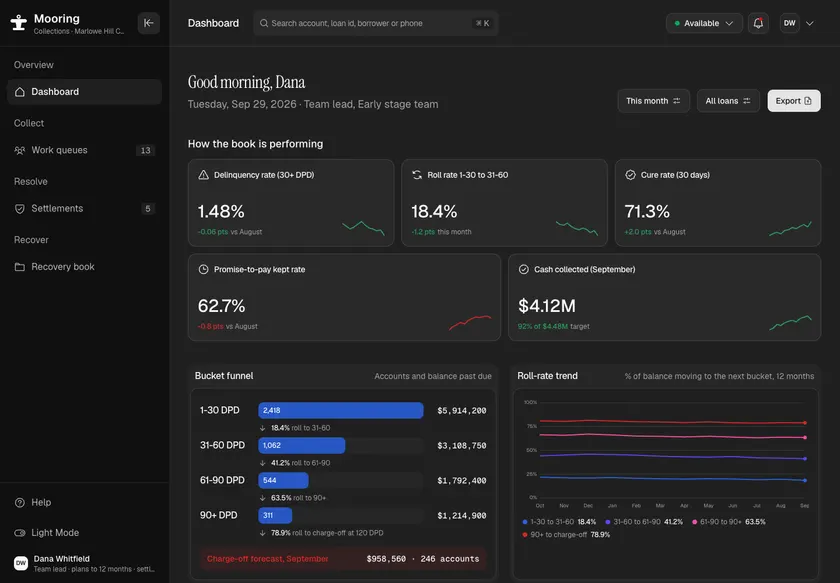
Mooring - Collections and Recovery Platform with Built-In Contact Guardrails
Designed and built a clickable collections and recovery platform for a US online lender of personal installment loans: work queues by delinquency bucket, a collector workspace that enforces call caps and contact windows on screen, settlements with approval limits, and a recovery book for charged-off accounts and agency placements.
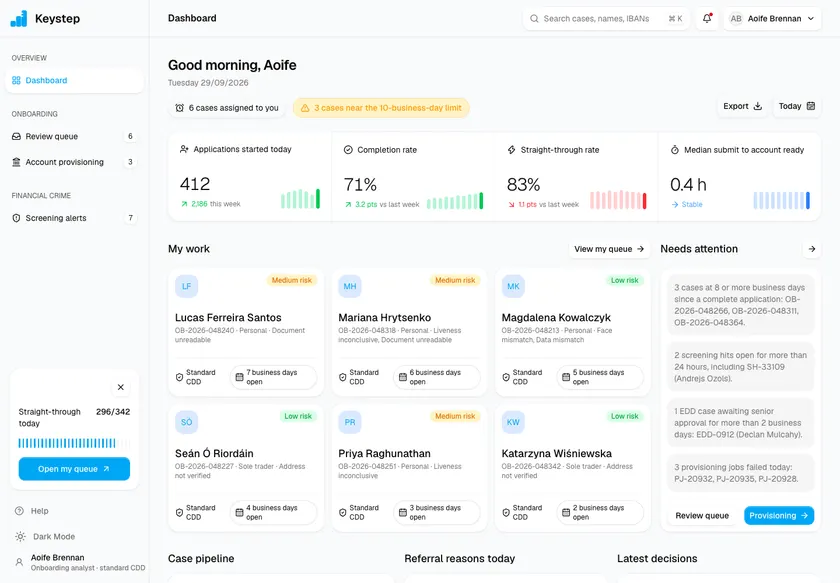
Keystep - Digital Bank Onboarding with ID, Liveness and Risk-Based Review
An onboarding platform for an Irish digital bank: applicants open a EUR current account from their phone with ID and selfie liveness checks, and a staff console lets onboarding and financial crime teams review the cases the rules cannot decide, through to an issued Irish IBAN.
The rules involved
The rules this kind of software usually has to follow. Guidance, not legal advice.
- 01
AML and KYC
Customer due diligence, sanctions screening, ongoing monitoring and periodic review, under each country's anti-money-laundering law.
- 02
Lending and consumer credit
Affordability checks, disclosures, fair treatment and notices when credit is refused. Credit scoring of people is high-risk under the EU AI Act.
- 03
Open banking and payments
PSD2 in Europe sets consent, strong customer authentication and access rules for bank APIs.
- 04
Operational resilience
Rules such as DORA in the EU and MAS TRM in Singapore set duties for IT risk, outsourcing and incident reporting.
- 05
Data protection
The GDPR and local privacy laws cover customer data, retention and automated decisions.
Framework guides
Rules our banking and lending builds cite most
- GDPR3
- PSD22
- UK GDPR2
- Account Aggregator framework1
- AML/CTF Act 20061
- AMLO Cap. 6151
- ASIC RG 2711
- Bank of England CHAPS Reimbursement Rules1
- Banking Act (Cap. 488)1
Two ways to work with OceanLab
Project build
We design and build the system as one project. It starts with a clickable prototype your team tries before any production code is written. Pay per milestone (outcome-based) or hourly at $30-50/hr, depending on role and seniority.
Embedded engineers
Our engineers join your team on a flexible monthly retainer. Part-time is fine and it runs month to month, with hours that overlap the US, UK and Europe, the Middle East, and Australia and Asia. Outcome-based or $30-50/hr.
Guides and tools
Banking and lending software questions
Can you build on top of our existing core banking system?
Yes. Most banking builds sit next to the core rather than replacing it: a console or workflow that reads and writes through the core's APIs, with its own audit trail and approvals.
How do you handle maker-checker and approvals?
Anything that moves money or changes a customer record can require a second person to approve it, with limits by role and amount, and every step logged.
Do you work with banks outside the US and Europe?
Yes. The banking builds on this page were made for many countries, each with its own rules, and the countries are counted from the case studies.
