Mooring - Collections and Recovery Platform with Built-In Contact Guardrails
Collections Platform for a US Consumer Lender
Designed and built a clickable collections and recovery platform for a US online lender of personal installment loans: work queues by delinquency bucket, a collector workspace that enforces call caps and contact windows on screen, settlements with approval limits, and a recovery book for charged-off accounts and agency placements.
Most of our work is under NDA. Per agreement, we can share the work but not the company details - all names and identifying information shown here have been changed.
Impact
Dashboard, work queues, account workspace, settlements and recovery book. Every one of the 36 demo accounts, including charged-off ones, opens its own workspace.
The dial is blocked at 7 attempts in 7 days, for 7 days after a conversation and outside 8:00 a.m. to 9:00 p.m. borrower time, with stricter state caps such as 2 in 7 for Massachusetts.
Collector to head of collections: plans from 6 to 24 months and post-charge-off discounts from 30% to 75%. Each settlement shows the approver it needs and why.
24 delinquent and 12 charged-off accounts, 13 settlements, 3 collection agencies, 8 staff users and 22 state rule sets.
The Problem
Marlowe Hill's collections team of about 60 people worked from a dialer, a spreadsheet of promises to pay, a shared inbox for disputes and the servicing system's notes field. Collectors could not see how often a borrower had been called that week, contact-frequency breaches were caught by a nightly report after they happened, settlements were approved by email, and two CFPB complaints in one quarter cited calls outside allowed hours.
Our Solution
Mooring follows a loan from the day it misses a payment to cure, a plan or settlement, or charge-off and recovery. Collectors work a queue that only offers accounts they may contact now, the account workspace enforces call caps, contact windows and holds before the dial, and settlements route to the right approver from a fixed authority grid.
The Challenge: Collecting Inside the Rules
US consumer collection is governed by federal law, state law and the lender's own policy, and the rules change with every account: where the borrower lives, what they agreed to, what they asked for and what has already happened this week.
Contact Limits Checked Too Late
Regulation F presumes compliance at no more than 7 calls in 7 days and no call within 7 days of a conversation, inside 8:00 a.m. to 9:00 p.m. at the borrower's location. Some states set lower caps. A nightly report found breaches only after the call was made.
First Party and Agencies, One Standard
Marlowe Hill collects in its own name, so it is a creditor rather than a debt collector under the FDCPA, while its agencies are debt collectors. Some states, such as California under the Rosenthal Act, apply collection rules to creditors too. The product applies the stricter rule by default.
Consent and Holds Per Channel
TCPA consent is held per phone number and can be revoked by any reasonable means. Cease requests, attorney representation, disputes, bankruptcy stays, deceased and SCRA cases each stop different things, and a collector has to know which before reaching for the phone.
Settlements and Recovery Without Limits
Plans were agreed on the phone with no fixed rules and settlements approved by email. Charged-off accounts sat with agencies whose remittance files nobody reconciled, and forgiven balances of $600 or more can need an IRS Form 1099-C.
Our Approach: From Collection Rules to a Clickable Platform
Spec and Rules Research
Mapped 9 user roles, 45 screens across staff, agency and borrower portals, and the data model for accounts, contact attempts, consents, state rule sets, promises, plans, settlements, placements and credit reporting. Wrote down the rules the design follows: FDCPA and Regulation F, TCPA, FCRA and Regulation V, UDAAP, state collection laws, SCRA, bankruptcy stays and charge-off at 120 days past due.
Clickable Demo on a Production UI Kit
Built 5 key screens on a production dashboard kit: the dashboard with KPIs, bucket funnel and roll-rate trend, work queues with a workable indicator derived from the guardrails, the account workspace with right-party verification, call-attempt strip and contact windows, settlements with the authority check, and the recovery book with placements, recalls and statute of limitations dates. All actions run on local state.
What a Production Build Adds
Integration with the loan servicing system (such as LoanPro or Nortridge), the dialer, Twilio and SendGrid messaging, Lob letters, card and ACH payments, Metro 2 credit reporting and e-OSCAR disputes, skip tracing, bankruptcy and deceased scrubs, the DMDC SCRA check and the FCC Reassigned Numbers Database. Staff auth by role, a full audit log kept for seven years, legal review of every state rule set, and the agency and borrower portals.
Why It Works: Guardrails Before the Dial
The Queue Only Offers Workable Accounts
Each account shows green to call now, amber for SMS or email only, or grey for no contact, with the reason on hover: call cap, state cap, 7-day post-conversation lock, borrower hours, inconvenient times or a hold. Work next opens the next account the collector may actually contact.
Blocked Actions Explain Themselves
Click-to-dial is disabled with the reason, a hold states what it blocks, and contact windows show in both borrower and collector time. When time zones disagree, only times that are convenient in every zone are allowed.
Nothing Disclosed Before Verification
Debt details stay behind a Verify first bar until the collector confirms the borrower's name plus two identifiers on the call, so nothing is said to a third party. Every message carries an opt-out line, and work email and phone are marked do not use unless the borrower asked.
Approvals From a Fixed Grid
A settlement lists its discount, structure, expiry and the approver it needs, with the agency net-back estimate and a 1099-C note when $600 or more is forgiven. Approve, decline or counter each needs a reason, and the written offer goes out before any payment.
Related case studies
View all: Banking & lending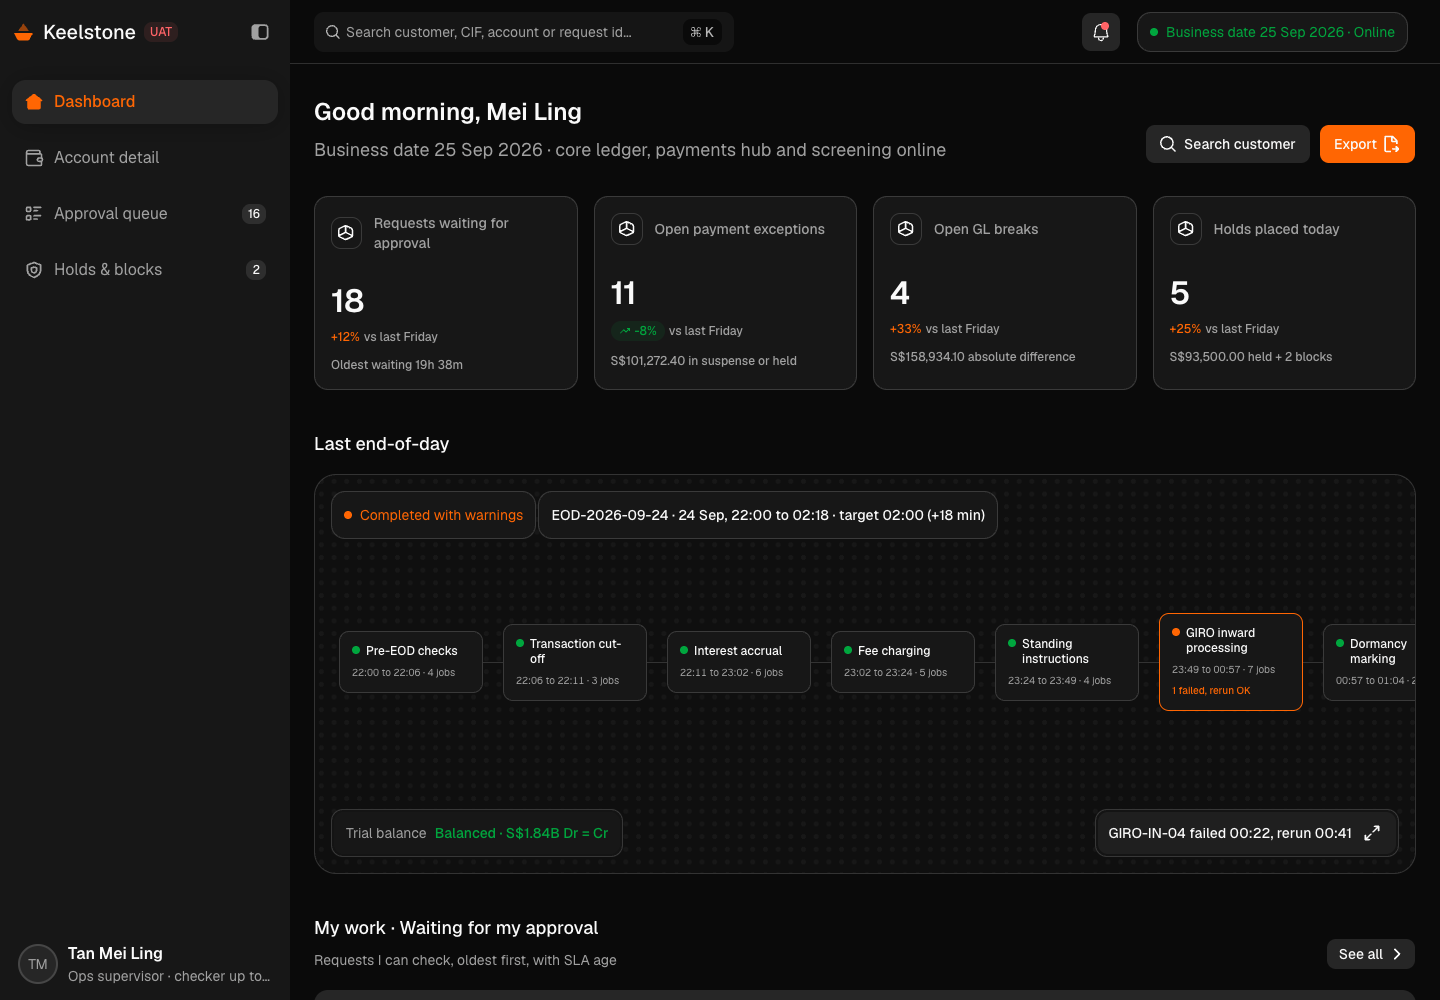
Keelstone - Core Banking Back-Office Console with Maker-Checker
Designed and built a clickable back-office console for a Singapore bank's deposit operations: holds and blocks, limit changes, fee waivers, payment repairs and end-of-day, with every money-moving change going through maker-checker approval.
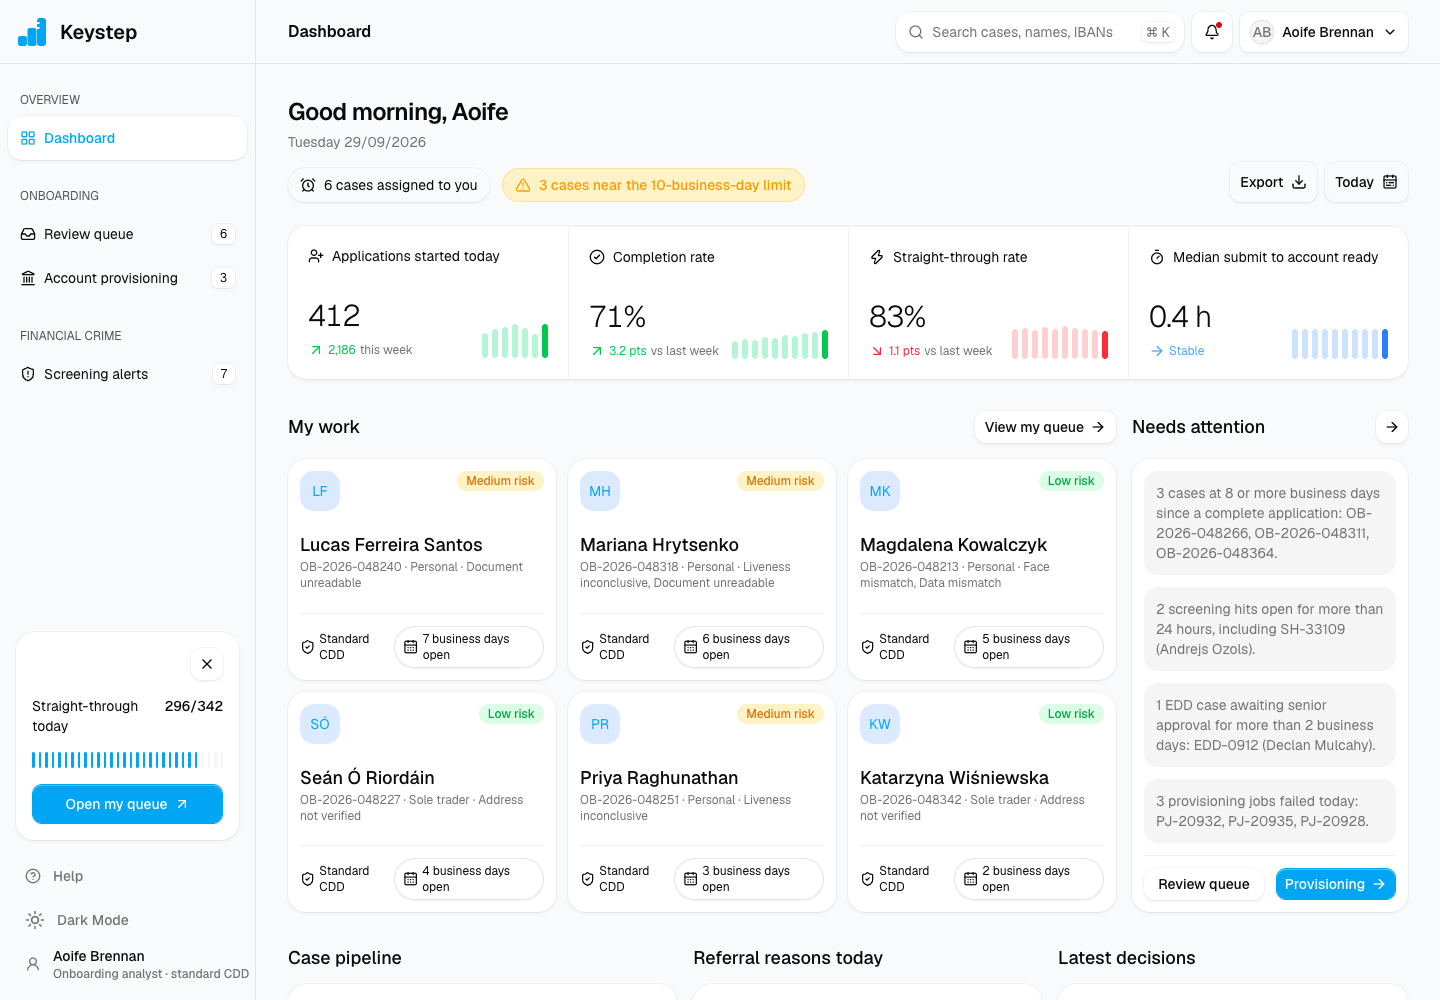
Keystep - Digital Bank Onboarding with ID, Liveness and Risk-Based Review
An onboarding platform for an Irish digital bank: applicants open a EUR current account from their phone with ID and selfie liveness checks, and a staff console lets onboarding and financial crime teams review the cases the rules cannot decide, through to an issued Irish IBAN.
Enterprise Software Engineering - Human + AI
Contact Us
© 2026 - Copyright. All Rights reserved Oceanlab
Location
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center

Enterprise Software Engineering - Human + AI
Contact Us
Locations
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center
© 2026 - Copyright. All Rights reserved Oceanlab