Lastro - Credit Scoring Engine with Explainable Decisions
Alternative-Data Credit Scoring for a Brazilian Digital Lender
A credit scoring engine for Ipê Crédito, a fictional Brazilian digital lender, that combines Cadastro Positivo bureau data, Open Finance account data and Pix patterns into one score, returns reason codes with every decision and keeps the model governance evidence risk, compliance and credit teams need.
Most of our work is under NDA. Per agreement, we can share the work but not the company details - all names and identifying information shown here have been changed.
Impact
Dashboard, model registry, model detail, decision explorer and decision detail, inside a 32-screen product spec.
Drawn from a 14-code library with Portuguese customer text, next to a feature contribution waterfall for every decision.
Development, validation, approved, shadow, challenger, champion and retired, with who moved each version and when.
Four bureaus, SCR, Open Finance, Serpro, the application form and internal history, with consent id and expiry on Open Finance inputs.
The Problem
Ipê Crédito scored applicants with a bureau score and a rules spreadsheet. A better model built on Open Finance and Pix data sat in notebooks because nobody could document, validate, run it beside the old score or explain a decline, and an LGPD review of one automated decision took the credit team two weeks to reconstruct.
Our Solution
We designed Lastro, a scoring engine where models are registered, validated, approved and monitored, and every decision is stored with its inputs, model version, feature contributions and reason codes - so a validator, the Banco Central do Brasil or a customer asking for a review gets an answer from the record.
The Challenge: Scoring Thin-File Borrowers Under Governance
Many of Ipê's customers have little bureau history but years of Pix and account activity. Scoring them fairly means new data sources, and new data sources mean more rules about consent, explanation and model risk.
Explaining Automated Decisions
Under LGPD Article 20 and the Cadastro Positivo law, a customer can ask for the main criteria behind a decision and request a review. Every score has to carry its reasons in plain Portuguese, owned by compliance rather than modellers.
Consent-Bound Open Finance Data
Open Finance Brasil data is shared only with explicit consent for a stated purpose and period. The engine must record the consent id and expiry with every pull and never score on data after the consent ends.
Model Risk the Board Can See
Banco Central supervision expects models to be documented, independently validated and monitored. A new model needs an inventory entry, a validator who did not build it and maker-checker approval before it takes traffic.
Fairness Without Protected Features
Sensitive data such as race, religion or health is never a feature, yet outcomes still have to be watched for gaps by age band, sex and region, with breaches blocking promotion until compliance reviews them.
Our Approach: Spec, Demo, Production Path
Spec and Rules Research
Mapped seven roles, from risk modeller and validator to credit analyst and compliance, and the rules they work under: LGPD, Cadastro Positivo, Open Finance Brasil consent, CMN model risk and expected-loss provisioning. The result is a 32-screen spec and a data model covering models, versions, features, decisions, reviews and an append-only audit log.
Clickable Demo on a Production UI Kit
Built five key screens on a production dashboard kit with deterministic mock data: the dashboard with KPIs, PSI stability and needs-attention items, the model registry, model detail with lifecycle rail and performance, calibration and stability tabs, the decision explorer with quick view and masked CPF search, and decision detail with reason codes, a contribution waterfall, inputs by source and shadow scores.
What a Production Build Adds
Live connections to Serasa Experian, Boa Vista, Quod, SPC Brasil, SCR, an Open Finance aggregator and Serpro, a Decision API with idempotency and consent checks, model training and registry on Databricks with MLflow, a feature store, validations, promotion requests, review handling, fairness and drift monitoring, role-based access with separation of duties and a tamper-evident audit log.
Why It Works: Every Score Carries Its Evidence
Decisions Answerable From the Record
Each decision stores the exact inputs, source response ids, consent references, model version, arm, cut-offs in force and reason codes, so a review request is answered by opening one page instead of reconstructing it.
Explanations Customers Can Read
Reason codes are ranked from each feature's contribution to the score and rendered in compliance-approved Portuguese, while analysts see the full waterfall behind them.
Safe Model Changes
Champion, challenger and shadow arms let a new model be scored beside the current one before it decides anything, with traffic routed by hashed CPF so a customer always lands in the same arm.
Privacy by Default
CPF and CNPJ are hashed before search and shown masked everywhere, sandbox traffic is visibly separated from production, and exports are masked and audited.
Related case studies
View all: Banking & lending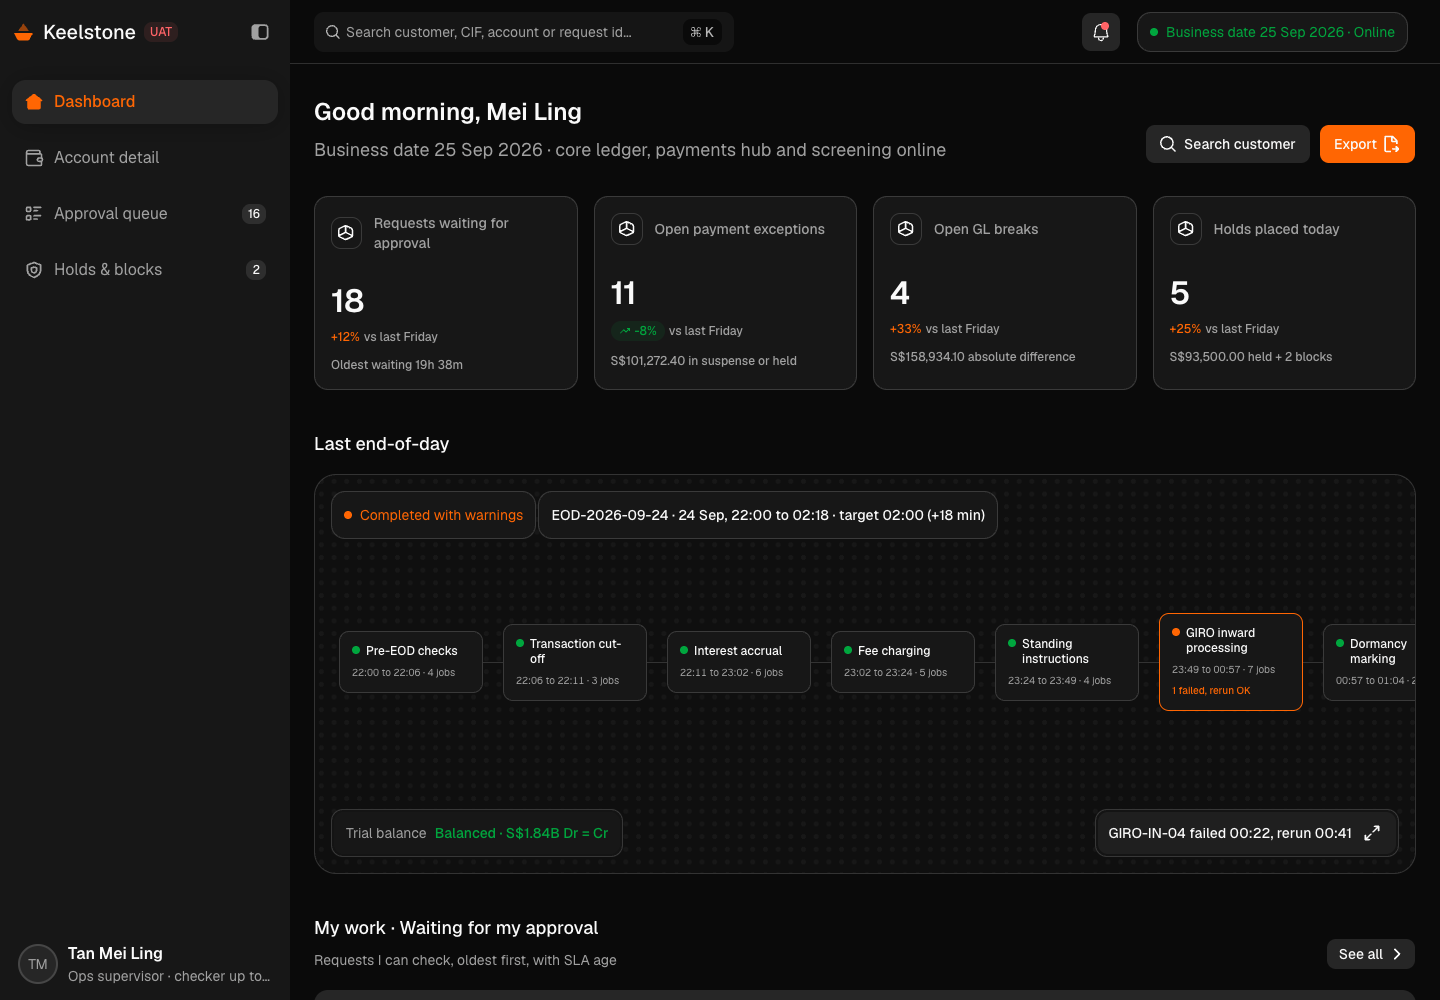
Keelstone - Core Banking Back-Office Console with Maker-Checker
Designed and built a clickable back-office console for a Singapore bank's deposit operations: holds and blocks, limit changes, fee waivers, payment repairs and end-of-day, with every money-moving change going through maker-checker approval.
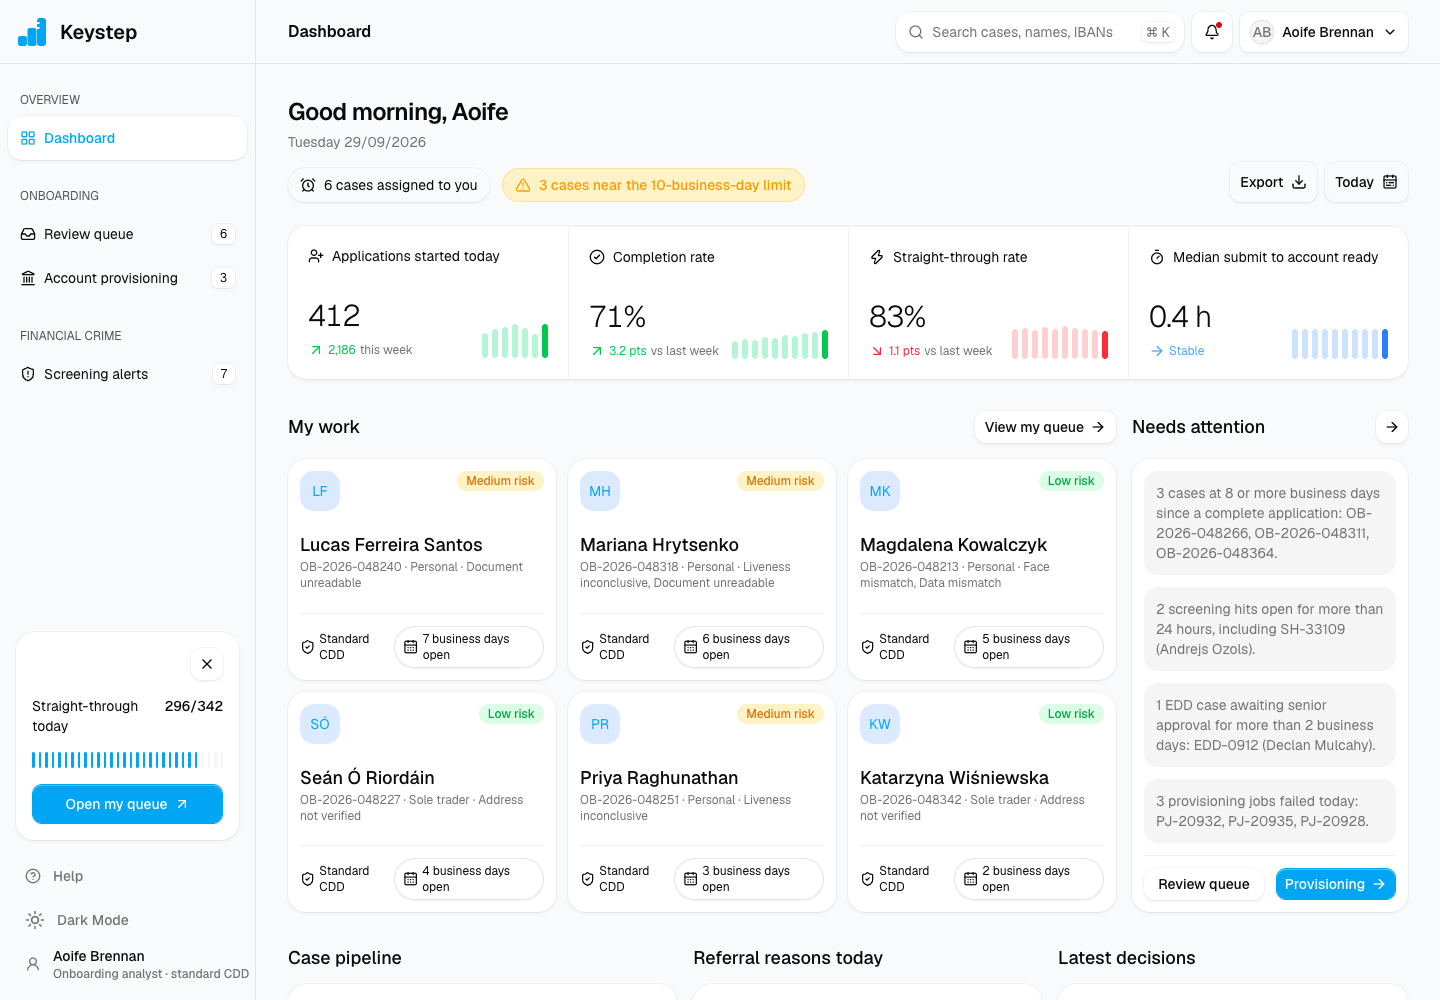
Keystep - Digital Bank Onboarding with ID, Liveness and Risk-Based Review
An onboarding platform for an Irish digital bank: applicants open a EUR current account from their phone with ID and selfie liveness checks, and a staff console lets onboarding and financial crime teams review the cases the rules cannot decide, through to an issued Irish IBAN.
Enterprise Software Engineering - Human + AI
Contact Us
© 2026 - Copyright. All Rights reserved Oceanlab
Location
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center

Enterprise Software Engineering - Human + AI
Contact Us
Locations
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center
© 2026 - Copyright. All Rights reserved Oceanlab