Quartet - Buy Now, Pay Later Platform with an Ops Console for Credit, Risk and Hardship
Interest-Free Split Payments for an Australian Credit Licensee
Designed and built a clickable ops console for an Australian buy now, pay later lender that splits online purchases of AUD 50 to AUD 3,000 into 4 or 8 fortnightly instalments: the health of the book, customer records, the fraud and referral queue and hardship cases with their regulatory deadlines.
Most of our work is under NDA. Per agreement, we can share the work but not the company details - all names and identifying information shown here have been changed.
Impact
Dashboard, customers, customer detail with 8 tabs, the fraud and referral queue and hardship, with slide-over panels for each case and actions like change limit, waive fee and start hardship.
AUD 8 on a missed instalment and AUD 6 more after 7 days, capped at the lesser of AUD 48 or 25% of the order, and paused while a hardship case is open.
Every hardship request shows its response due date from receipt, turning red within 5 days. Referred applications show the 30-minute merchant hold counting down.
Orders and instalment schedules generated from the plan rules, 10 merchants, 8 staff, 10 referrals, 13 hardship cases and 6 complaints, one of them at AFCA.
The Problem
Kestrel Point ran its BNPL product on a white-label checkout it could not change, a spreadsheet of merchant settlements and a shared inbox for hardship and complaints. When BNPL came under the credit laws in 2025, it had to show a documented unsuitability assessment behind every approval, hardship requests answered on time and complaints tracked to their deadlines. The old stack could do none of that, and hand-keyed refunds took up to a week to reach shoppers.
Our Solution
Quartet covers the shopper checkout and app, a merchant dashboard and an ops console for Kestrel Point's own team. The build delivers the ops console: credit analysts, care agents and hardship officers see what is waiting and how close it is to its deadline, decide referred applications with the rules and signals in front of them, and build hardship arrangements with a preview of the new schedule.
The Challenge: BNPL Under the Credit Laws
Since 2025, BNPL contracts in Australia are regulated as low cost credit contracts. A checkout that decides in seconds now has to leave a responsible lending record, keep fees under a cap and answer hardship and complaints on a regulatory clock.
Instant Decisions That Leave a Record
Responsible lending applies before every contract and every limit increase. Each approval must record the inquiries made, the data used and the outcome, while the shopper waits at checkout and the merchant holds the order for at most 30 minutes.
Fees Under a Cap
No interest is charged, and fees are capped by regulation to stay a low cost credit contract. Late fees have to stop at the per-order cap, track each customer's rolling 12-month total and pause while a hardship arrangement is in place.
Hardship and Complaint Deadlines
Hardship requests generally need a response within 21 days. Complaints follow ASIC RG 271: acknowledged within 1 business day and answered within 30 days, or 21 for hardship-related complaints, with AFCA rights in every final response.
Three Audiences, Eleven Roles
Shoppers, merchant owners, staff and developers, and Kestrel Point's analysts, care agents, hardship and complaints officers, merchant operations, compliance and admins each need a different view of the same orders, customers and credit records.
Our Approach: From Credit Rules to a Clickable Console
Spec and Rules Research
Mapped 11 roles and 41 screens: 11 for shoppers, 11 for merchants and 19 for the ops console, plus slide-over panels and about 18 modals. Defined the data model for customers, situation checks, assessments, orders, schedules, hardship cases, complaints and credit reporting, and wrote down the rules the design follows: the NCCP Act and National Credit Code, ASIC RG 271, design and distribution obligations, the Privacy Act and Credit Reporting Code, AML/CTF and PCI DSS.
Clickable Demo on a Production UI Kit
Built the ops console's 5 key screens on a production dashboard kit: the dashboard with KPIs, decisions today, arrears ladder and regulatory deadlines; customers with status and flag filters; customer detail with orders, payments, credit, credit reporting, hardship and complaints; the fraud and referral queue with rules triggered, identity and device signals and approve, decline, request ID or block; and hardship with an arrangement builder that previews the new schedule.
What a Production Build Adds
The shopper checkout and app, the merchant dashboard and the remaining ops screens for limit reviews, decision rules, arrears, complaints, merchants, credit reporting, reports and the audit log. Integrations with Equifax, Experian or illion, identity verification through DVS, Consumer Data Right bank data, hosted card fields and PayTo, NPP payouts to merchants, fraud and device signals and e-commerce plugins. An append-only audit log for every decision, limit change, fee waiver and hardship outcome.
Why It Works: Deadlines and Rules on the Screen
The Clock Is Always Visible
Referrals show minutes left on the merchant hold, hardship cases show days left to respond, and the dashboard lists hardship, complaint and AFCA deadlines. Staff work the case closest to its deadline first.
Decisions Show Their Reasons
A referred application lists each rule that fired with its value and outcome, next to the identity results, device and fraud signals and bureau summary. A decline carries a customer-facing reason.
Hardship Built to Help
The officer sees the customer's own words, their income and essentials, and the balance by order, then builds a pause, reduced instalments or new dates and sees the new schedule before offering it. Late fees are paused while the case is open.
One Place for One Customer
Customer detail brings the limit, available to spend, balance and unpaid fees together with flags for hardship, open complaints and vulnerability, so a care agent does not have to piece the story together from separate tools.
Related case studies
View all: Banking & lending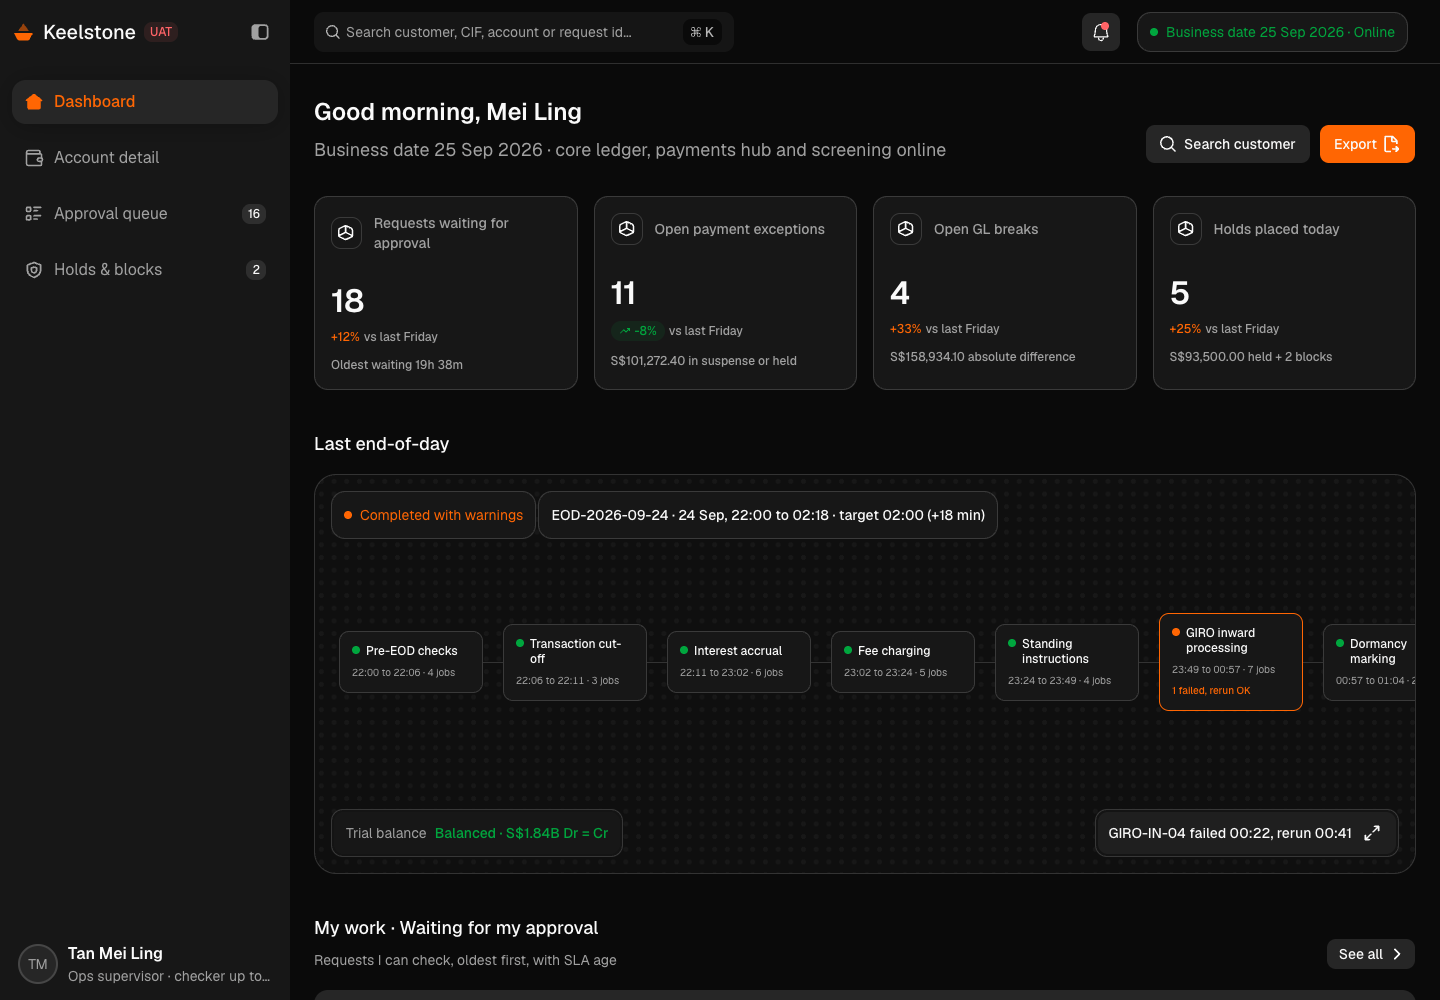
Keelstone - Core Banking Back-Office Console with Maker-Checker
Designed and built a clickable back-office console for a Singapore bank's deposit operations: holds and blocks, limit changes, fee waivers, payment repairs and end-of-day, with every money-moving change going through maker-checker approval.
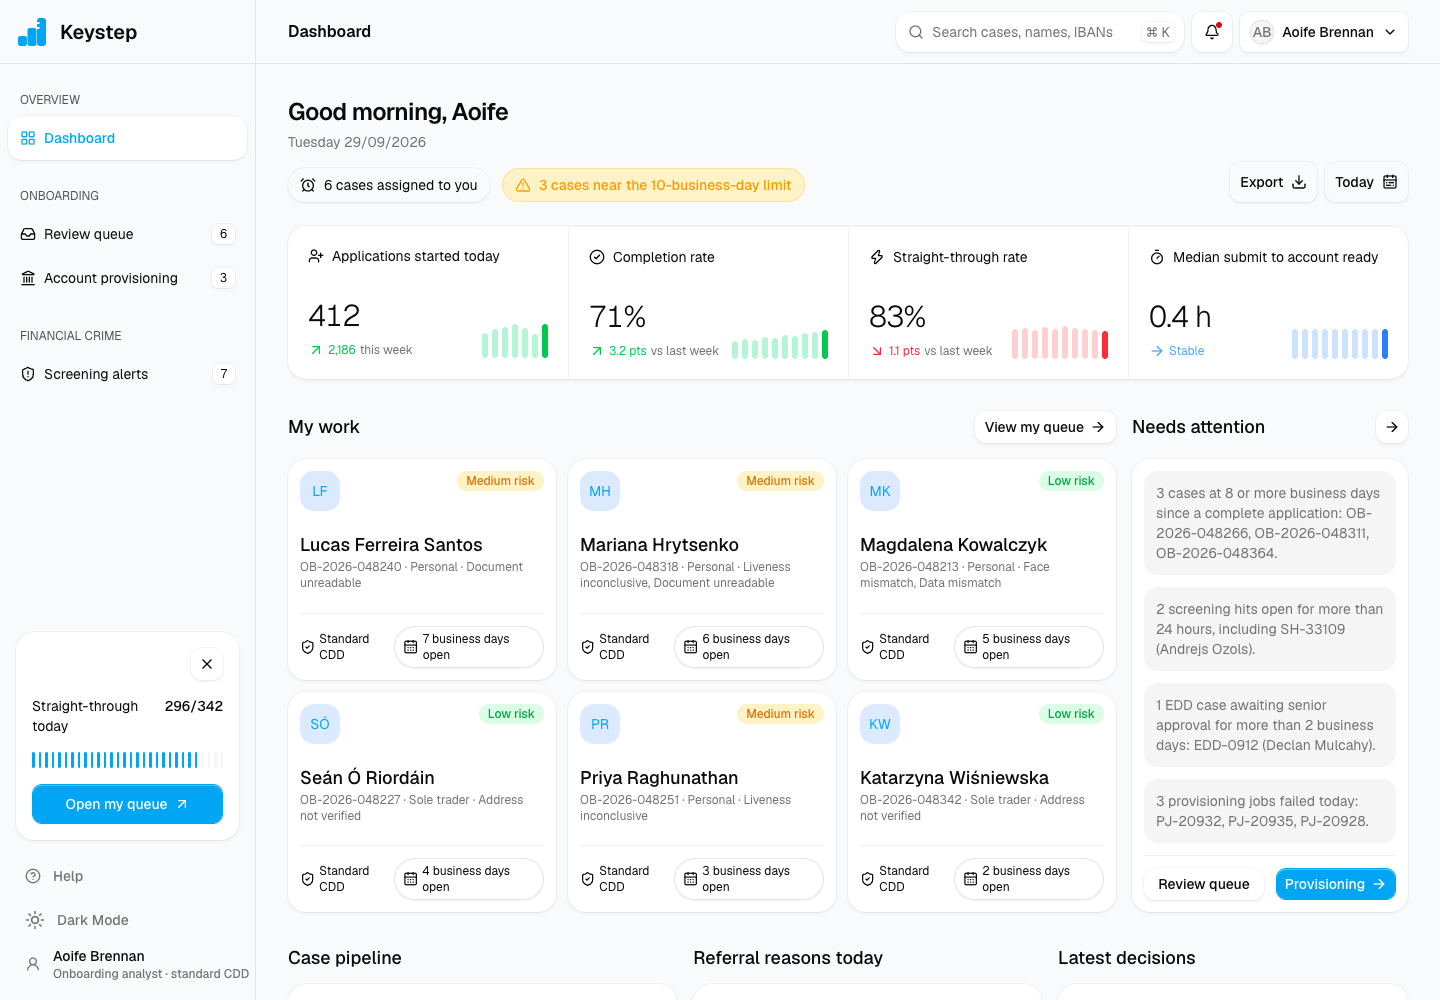
Keystep - Digital Bank Onboarding with ID, Liveness and Risk-Based Review
An onboarding platform for an Irish digital bank: applicants open a EUR current account from their phone with ID and selfie liveness checks, and a staff console lets onboarding and financial crime teams review the cases the rules cannot decide, through to an issued Irish IBAN.
Enterprise Software Engineering - Human + AI
Contact Us
© 2026 - Copyright. All Rights reserved Oceanlab
Location
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center

Enterprise Software Engineering - Human + AI
Contact Us
Locations
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center
© 2026 - Copyright. All Rights reserved Oceanlab