Lintel - Residential Mortgage Portal with Stress-Tested Underwriting
Mortgage Platform for a Canadian Trust Company
Designed a residential mortgage portal for a Canadian trust company's borrowers, brokers and staff, and built a clickable staff workspace: deal pipeline, deal detail, an underwriting workbench that runs the stress test and checks lending authority, and a conditions desk that tracks every condition against the closing date.
Most of our work is under NDA. Per agreement, we can share the work but not the company details - all names and identifying information shown here have been changed.
Impact
Dashboard, deal pipeline (board and table), deal detail, underwriting workbench and conditions desk, with a role switcher across 5 staff roles.
GDS and TDS at the contract rate and the qualifying rate side by side: the greater of contract + 2% or the 5.25% floor, recalculated live as the underwriter changes the final terms.
GDS 39% and TDS 44% at the qualifying rate, Beacon minimum 650, 80% conventional LTV, the CAD 1,500,000 insured price cap, amortization limits and agent licence by province, each marked pass, exception or fail.
Purchases, refinances and switches across Ontario, British Columbia, Alberta and Quebec, from 6 brokerages and 7 licensed agents, with applicants, credit reports, documents and conditions.
The Problem
Birchmount's underwriters received broker deals through a submission platform, then worked them in email, a shared drive and a spreadsheet of conditions. Borrowers' pay stubs and Notices of Assessment arrived in batches through brokers, nobody could say which conditions were still open three days before closing, insurance submissions were re-keyed into each insurer's portal, and renewals lived in a calendar reminder, so some maturing mortgages quietly left.
Our Solution
Lintel puts the deal, the evidence and the decision in one place. Underwriters see the stress test and every policy rule before they decide, the screen checks their lending authority and refers the deal when it is beyond it, and administrators clear conditions grouped by deal against the closing date, with the borrower, broker, lawyer or internal owner on every one.
The Challenge: One Deal, Many Rules and Many Hands
About 80% of Birchmount's deals come through mortgage brokers in four provinces. Every one passes through underwriters, administrators, insurers and a closing lawyer or notary, and each step follows federal or provincial rules.
Conditions Nobody Could See
Conditions lived in a spreadsheet and documents in email and a shared drive. Three days before closing, no one could say which conditions were still open, or who owned them: the borrower, the broker, the lawyer or Birchmount.
Two Rates for Every Ratio
Under OSFI Guideline B-20, uninsured borrowers are qualified at the greater of the contract rate plus 2% or a 5.25% floor, not the rate they will pay. GDS and TDS have to be shown at both rates, and the basis recorded on every deal, including exempt straight switches.
Insured and Conventional Rules
Under 20% down, the mortgage needs default insurance from CMHC, Sagen or Canada Guaranty, with a price cap of CAD 1,500,000, a minimum down payment and a 25-year amortization (30 for first-time buyers and new builds). Conventional loans are capped at 80% loan-to-value.
Four Provinces, Four Regulators
Brokers are licensed by FSRA, BCFSA, RECA or the AMF, and must be active in the property's province. Quebec deals close with a notary and fall under Law 25, every borrower needs a FINTRAC identity record, and borrower-facing text exists in English and French.
Our Approach: From Lending Rules to a Clickable Workspace
Spec and Rules Research
Mapped 10 user roles, from underwriter to broker agent and borrower, and 40 screens: 30 for staff, 4 in the broker portal and 6 in a mobile-first borrower portal. Defined the data model for deals, applicants, conditions, commitments, funding and renewals, and wrote down the rules: the OSFI B-20 stress test, GDS and TDS, mortgage default insurance, FINTRAC identity checks, PIPEDA and Quebec's Law 25, provincial broker licensing and cost of borrowing disclosure.
Clickable Demo on a Production UI Kit
Built 5 key staff screens on a production dashboard kit: the dashboard with a 10-day closings strip and pipeline by stage, the deal pipeline as a board and a table, the deal detail with applicants, income, down payment, documents and activity, the underwriting workbench with affordability, credit, policy rules and an authority check, and the conditions desk. Ratios, LTV and insurance premiums are computed from the data, and decisions, referrals and condition changes update every screen.
What a Production Build Adds
Integrations with Filogix and Velocity for broker submissions, Equifax and TransUnion for credit, CMHC, Sagen and Canada Guaranty for insurance, appraisal and identity providers, FCT for lawyer instructions, DocuSign for commitments and Lynx or EFT for funding. Sign-in with two-factor authentication for broker agents, an audit log of every approval, waiver and funding release, and the remaining screens: broker and borrower portals, commitments, funding with a second approver, renewals and FINTRAC records.
Why It Works: The Rules Are on the Screen
The Stress Test Shows Its Working
The workbench prints the rule it applied, such as "Contract 4.64% + 2% = 6.64%, above 5.25% floor", and shows the ratios at both rates against their limits. Change the amount, rate or amortization and the ratios recalculate before the decision is recorded.
Authority Decides the Button
Before a decision, the screen checks the loan amount, LTV and any policy exceptions against the user's lending authority. When a co-borrower's Beacon score is below 650, an underwriter's Record decision becomes Refer to senior, and only a senior underwriter can approve the exception or waive a condition.
Conditions Measured Against Closing
The dashboard flags closings with open conditions, pipeline cards turn amber or red as closing nears, and the conditions desk groups every condition by deal with "3 of 9 conditions cleared", its owner, due date and evidence.
Each Role Starts With Its Own Work
Underwriters see their assigned deals oldest first, administrators see conditions waiting for review, funding officers see closings in the next 5 business days and renewals officers see maturities without an offer. The account menu switches between the 5 roles in the demo.
Related case studies
View all: Banking & lending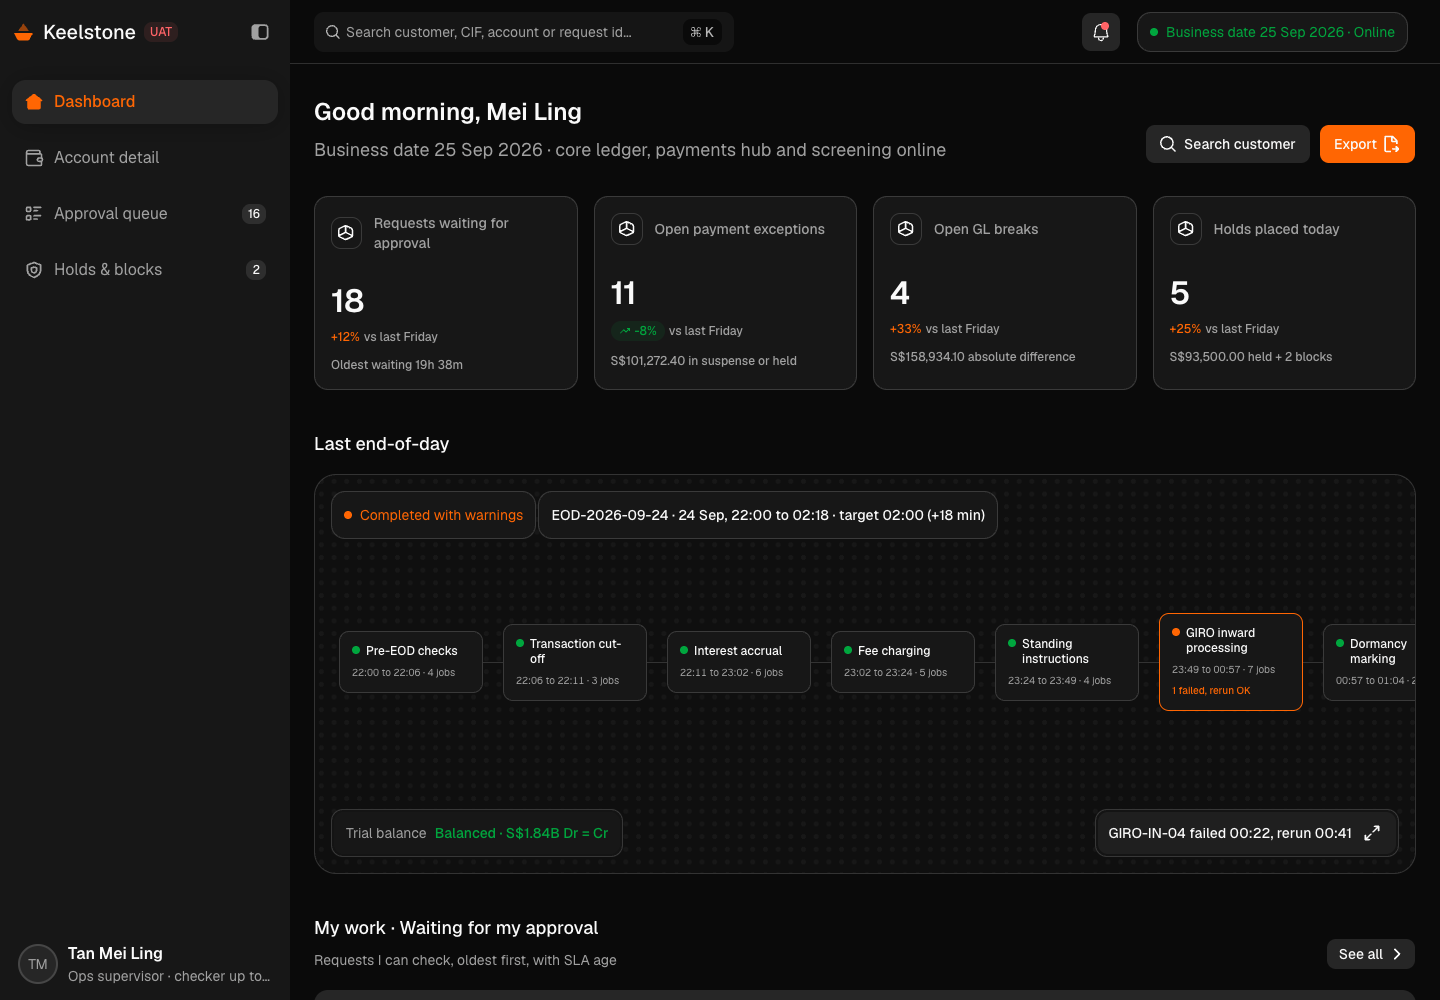
Keelstone - Core Banking Back-Office Console with Maker-Checker
Designed and built a clickable back-office console for a Singapore bank's deposit operations: holds and blocks, limit changes, fee waivers, payment repairs and end-of-day, with every money-moving change going through maker-checker approval.
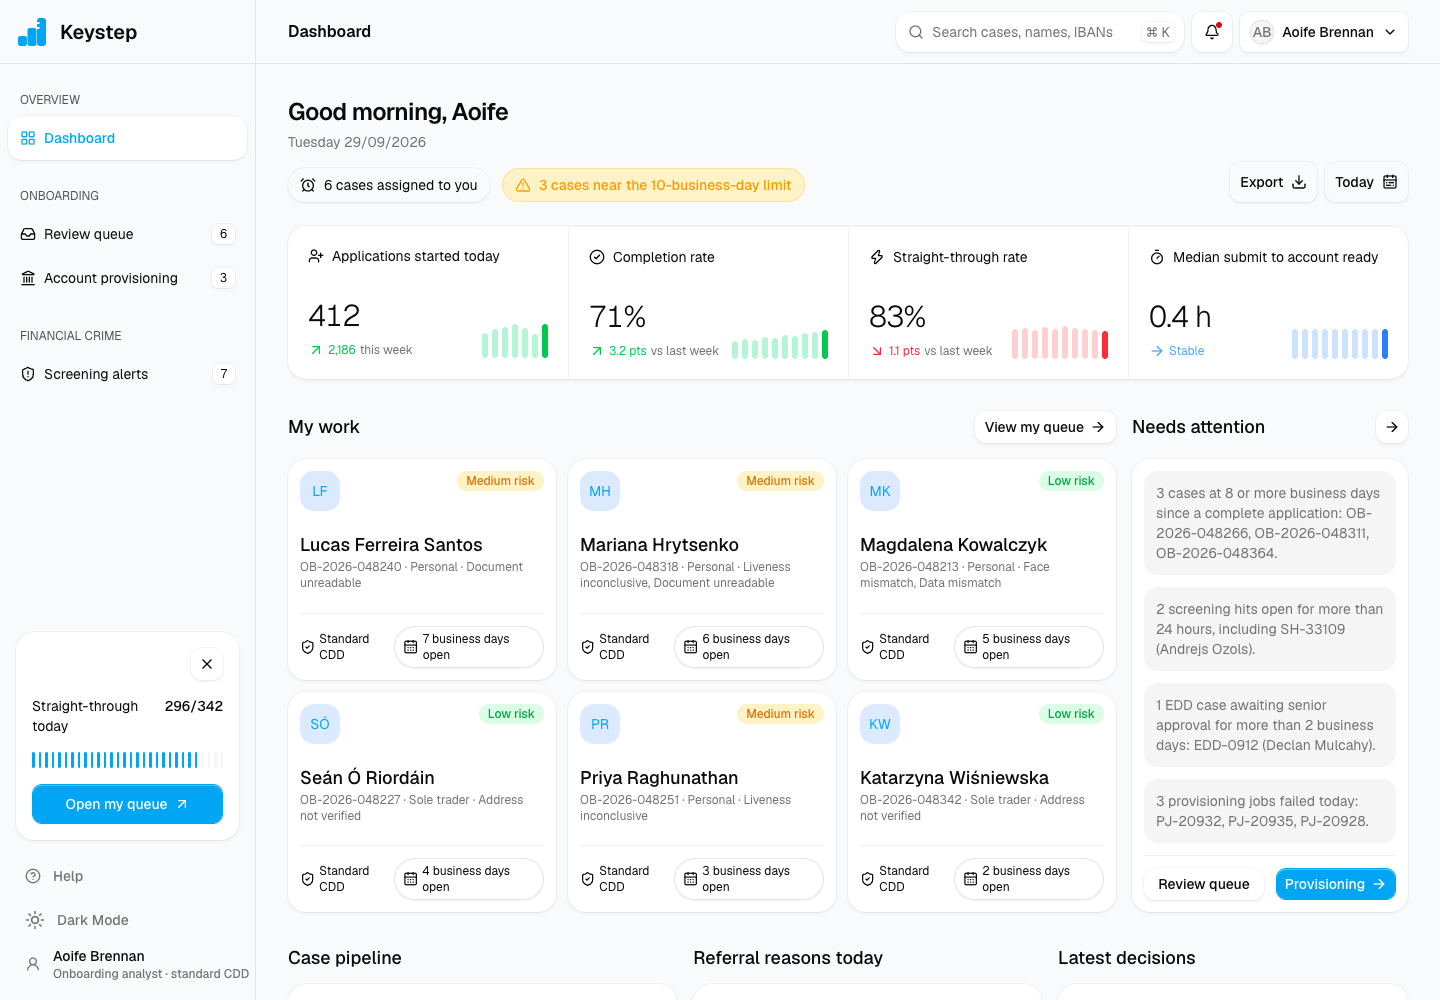
Keystep - Digital Bank Onboarding with ID, Liveness and Risk-Based Review
An onboarding platform for an Irish digital bank: applicants open a EUR current account from their phone with ID and selfie liveness checks, and a staff console lets onboarding and financial crime teams review the cases the rules cannot decide, through to an issued Irish IBAN.
Enterprise Software Engineering - Human + AI
Contact Us
© 2026 - Copyright. All Rights reserved Oceanlab
Location
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center

Enterprise Software Engineering - Human + AI
Contact Us
Locations
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center
© 2026 - Copyright. All Rights reserved Oceanlab