Fjärd - Robo-Advisor App for ISK and KF Savings
Robo-Advisor App for a Swedish Investment Manager
Designed and built a clickable robo-advisor app for a Swedish digital investment manager: a suitability-based portfolio recommendation with its costs shown before investing, managed ISK and KF accounts that rebalance automatically, goals with projections, ISK tax estimates, and deposits and withdrawals signed with BankID.
Most of our work is under NDA. Per agreement, we can share the work but not the company details - all names and identifying information shown here have been changed.
Impact
Home, account detail with Allocation, Holdings, Sustainability, Costs and ISK or KF tax tabs, goals, activity and the recommended portfolio, plus Deposit and Withdraw sheets signed with BankID.
The customise slider allows any lower risk level, or one level above the recommendation with a warning and an extra confirmation. Two or more levels higher is not offered.
The recommendation breaks year 1 costs into Tallbacka's 0.24% fee, 0.22% fund costs and 0.03% transaction costs, in SEK and %, and shows their effect on return after 12 years.
3 ISK and 1 KF across 5 goals, 12 funds and ETFs with SFDR and PRIIPs data, 4 model portfolios, 28 transactions and 6 inbox notices.
The Problem
Tallbacka started as a traditional manager with a 500,000 SEK minimum, paper suitability forms and a portfolio manager rebalancing accounts from a spreadsheet. Savers with 500 SEK a month were out of reach, each new customer took an adviser about 90 minutes, contradictory suitability answers went unnoticed, and rebalancing ran once a quarter at best, so portfolios drifted far from their target risk.
Our Solution
Fjärd lets customers sign up with BankID, answer a suitability questionnaire and receive a recommended portfolio of low-cost index funds and ETFs with the reasons and costs explained. Tallbacka then manages each ISK or KF on a discretionary basis: monthly savings by autogiro, automatic rebalancing, withdrawals and ISK tax information, with a record of why every recommendation was made.
The Challenge: Automated Advice That Stays Suitable
A robo-advisor in Sweden is still an investment firm supervised by Finansinspektionen. Every portfolio has to be suitable for the person holding it, every cost disclosed in advance, and the algorithm has to be explainable and overseen by people.
Suitability Without an Adviser
MiFID II requires a suitability assessment of knowledge and experience, financial situation and risk tolerance. ESMA's guidelines for robo-advice expect questions that detect inconsistent answers, a clear explanation of how the algorithm works and human oversight of it.
Sustainability Preferences by Law
Since August 2022 the assessment must ask for a minimum share in taxonomy-aligned and SFDR sustainable investments and whether principal adverse impacts should be considered. The portfolio has to meet those preferences, or the customer has to adapt them on record.
Costs and Alerts Owed to the Customer
Costs and charges must be shown before investing and reported yearly, in SEK and %, including their effect on return. Portfolio management customers must be told when their portfolio falls 10% since the last periodic statement, the same business day.
Two Account Types, Two Tax Regimes
An ISK is taxed on a capital base times a standard rate, with a tax-free amount per person across all providers. A KF is owned by a partner insurer that pays yield tax and names beneficiaries. Customers need both explained in plain language.
Our Approach: From Suitability Rules to a Clickable App
Spec and Rules Research
Mapped 8 roles from customer to compliance, 48 screens across the customer app and the staff console, and the data model for questionnaire versions, risk assessments, recommendations, review cases, model portfolios, instruments, accounts, rebalancing runs, order batches and ISK tax years. Wrote down the rules the design follows: MiFID II suitability and cost disclosure, ESMA's robo-advice guidelines, sustainability preferences, PRIIPs KIDs, ISK and KF tax, investor protection, the Swedish AML Act and GDPR.
Clickable Demo on a Production UI Kit
Built 5 key customer screens on a production dashboard kit: Home with total value, goals and the latest notice, account detail with drift from target, holdings with KID links, sustainability shares, costs and ISK tax, goals with a projection fan chart, activity with filters and trade details, and the recommended portfolio with risk dial, reasons, Bred or Hållbar line, costs and the customise rule. Deposits, withdrawals and BankID signing run on local state.
What a Production Build Adds
BankID login and signing, SPAR, Tink, autogiro through Bankgirot, Swish, a fund platform such as MFEX or Allfunds, an ETF broker over FIX, the custodian, Morningstar and MSCI ESG data, screening, Skatteverket reporting and the partner insurer's API. The remaining onboarding and customer screens in Swedish and English, and the staff console: suitability review queue with four-eyes approval, model portfolios, the daily rebalancing engine, order batches, reconciliation and an audit log.
Why It Works: Every Recommendation Explained
Reasons Built From the Customer's Answers
The recommendation explains itself in plain sentences taken from the questionnaire, such as the 12-year horizon and the 25% fall the customer said they could accept, with a How we decided link to the method behind the risk level.
Costs Before Commitment
Before opening an account the customer sees year 1 costs in SEK and %, the projected value with and without costs, and a fan chart of poor, expected and good outcomes labelled as a forecast, not a promise.
Guardrails on Risk and Knowledge
Failed test questions show a knowledge warning the customer must acknowledge, choosing a higher risk level needs an extra confirmation, and a goal with under 3 years left suggests a risk review.
Drift and Tax in Plain View
Each account shows target against current weight per fund and the drift from target, with the 3 percentage point rebalancing rule stated. The ISK tab works through the capital base, standard rate and tax-free amount for this year's estimate.
Related case studies
View all: Wealth & investing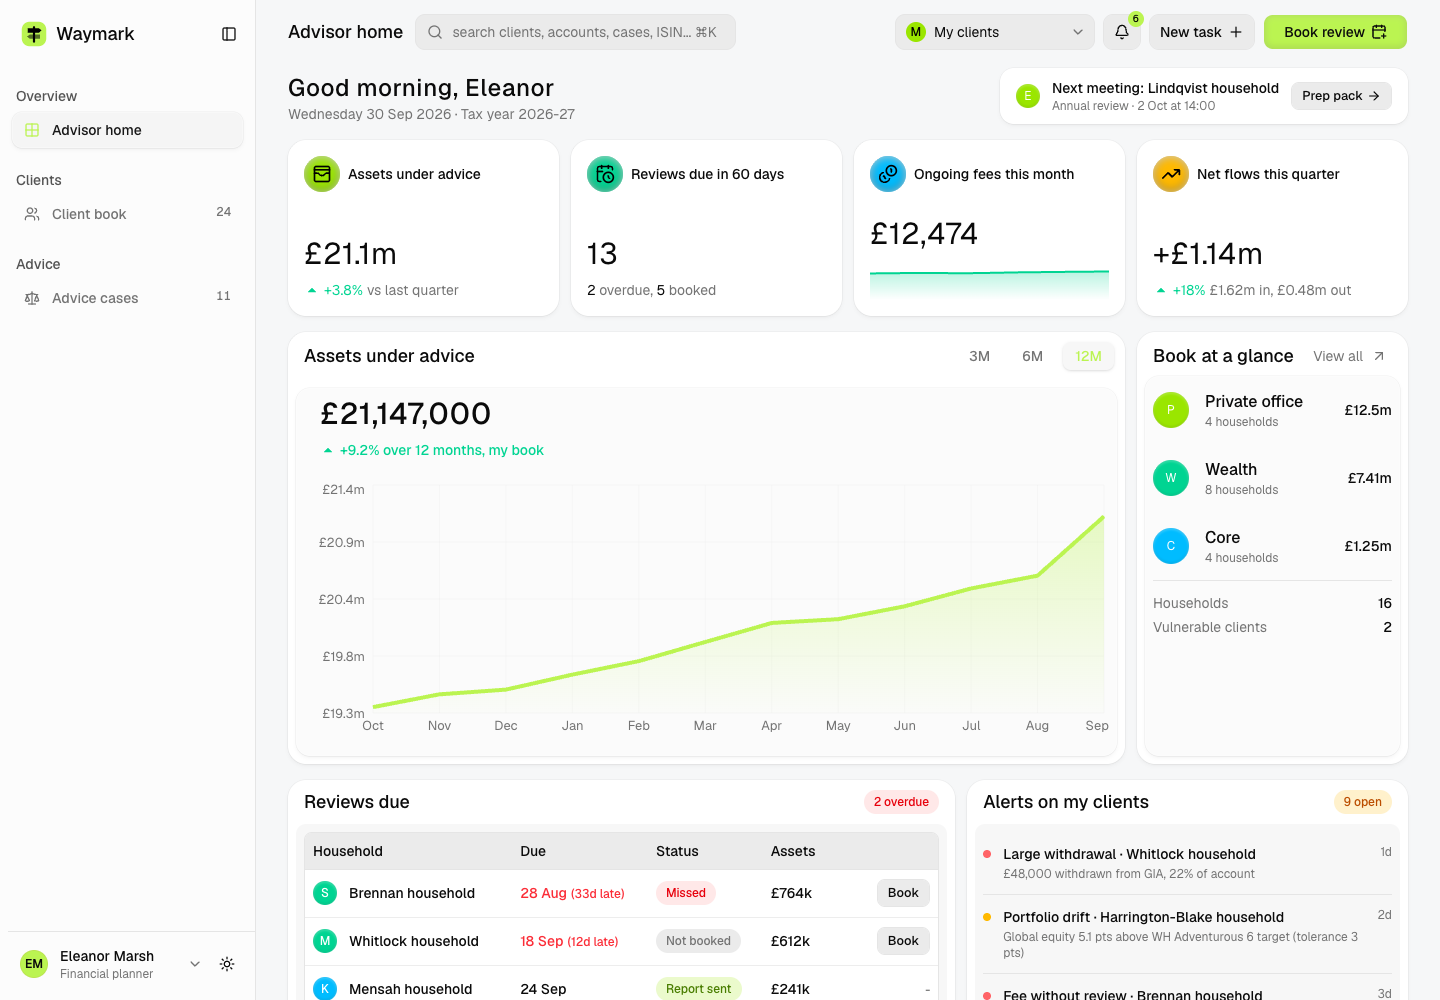
Waymark - Advisor Portal with Suitability Reports Built From the Case
Designed and built a clickable advisor portal for a UK wealth firm's financial planners: a daily home with reviews due and alerts, a segmented client book, a Client 360 for every household, an advice case board and a suitability report builder that will not issue a report until the checks and approvals are in place.
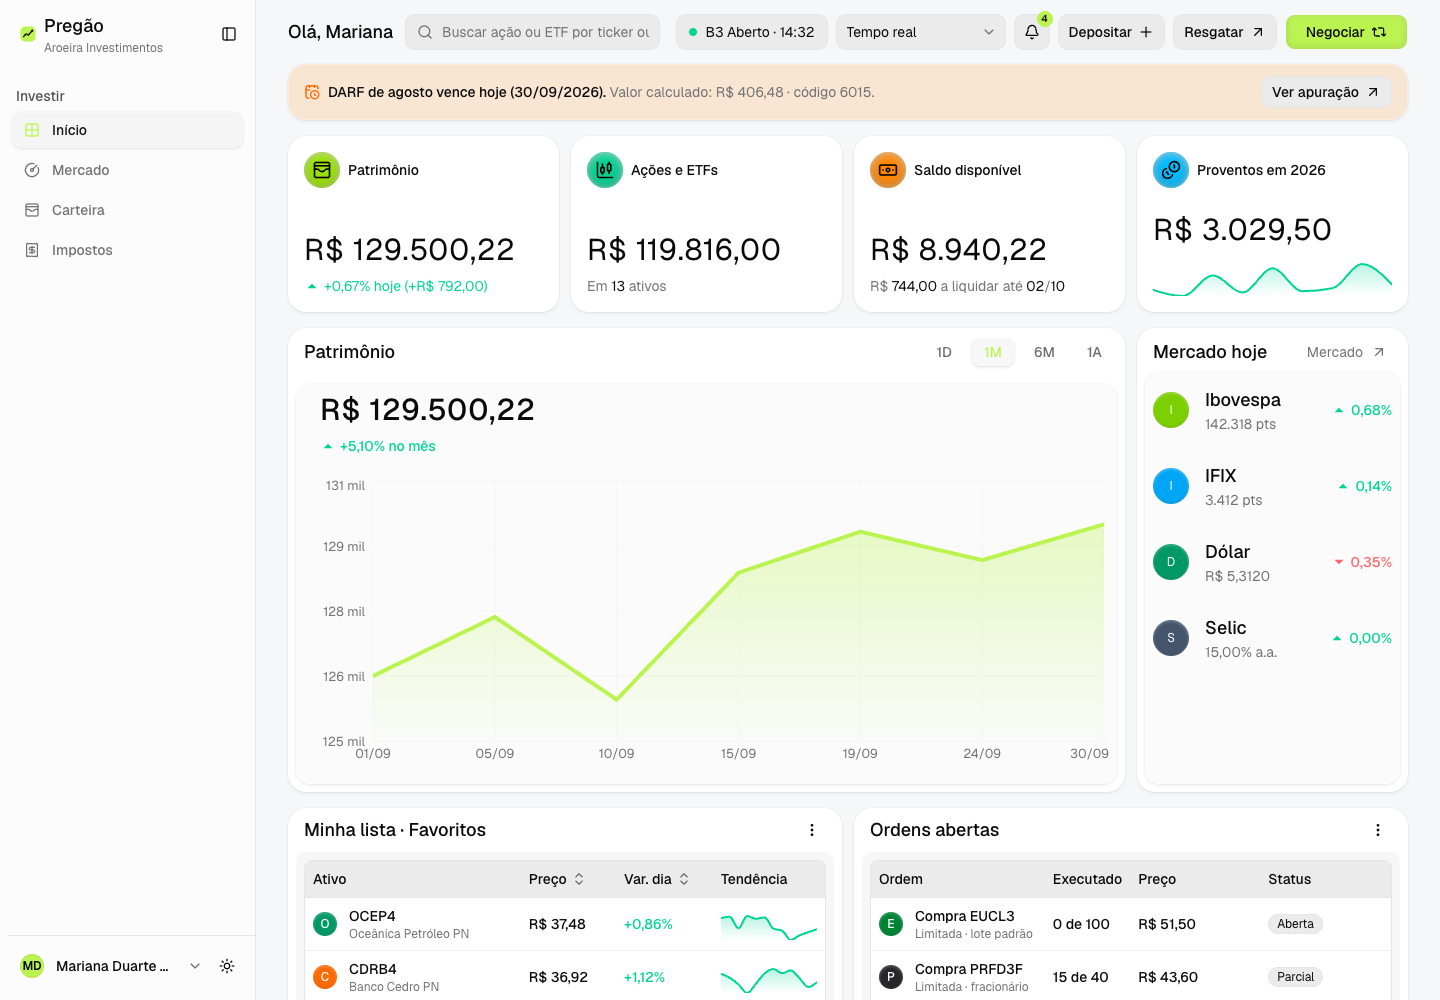
Pregão - Stock and ETF Trading App with the Income Tax Explained
Designed and built a clickable investor app for a Brazilian broker trading B3 stocks and ETFs: patrimônio at a glance, a market overview, an asset page with an order ticket that shows the lot and fractional split before sending, a portfolio at average price, and a tax centre that works out the monthly DARF.
Enterprise Software Engineering - Human + AI
Contact Us
© 2026 - Copyright. All Rights reserved Oceanlab
Location
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center

Enterprise Software Engineering - Human + AI
Contact Us
Locations
Global Headquarters
21 Merchant Road, 3rd Floor, Singapore 058267
Main corporate office and leadership operations
North America Office
548 Market Street, PMB 12345, San Francisco, CA 94104
Client operations and business development
India Office
402 Shivalik Shilp II, SG Highway, Ahmedabad 380015
Engineering and delivery center
© 2026 - Copyright. All Rights reserved Oceanlab